Blog

What Documents Do You Need for a Hard Money Loan in Arizona?

What Documents Do You Need for a Hard Money Loan in Arizona?

What Documents Do You Need for a Hard Money Loan in Arizona?

Hard money lending can move considerably faster than conventional bank financing, but fast does not mean paperwork free. A lender still needs enough information to understand the property, the proposed transaction and how the loan will be structured.

Preparing the right documents before you find a property can save valuable time later. The exact requirements depend on whether you are an investor, an owner occupant, purchasing property or refinancing an existing loan.

Start With the Property Information

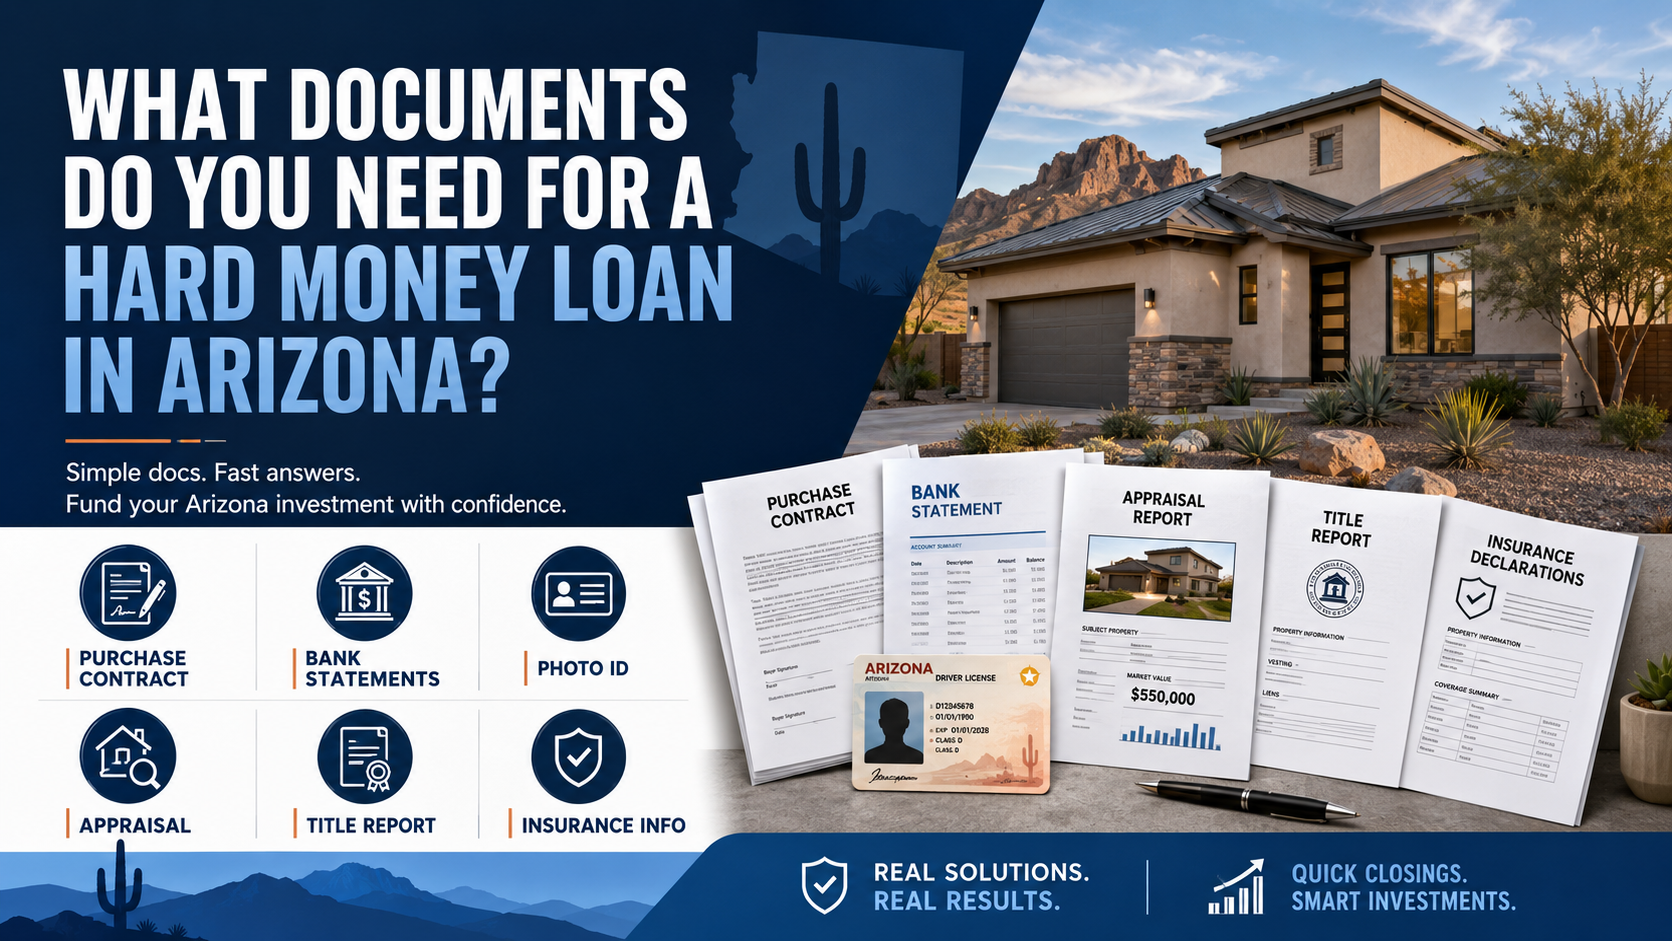
For a purchase, the accepted real estate contract is one of the most important documents.

The lender needs to know the purchase price, property address, closing timetable and any terms that affect the proposed financing. Brad Loans asks borrowers who are already under contract to provide a copy of the purchase contract as part of its loan process.

An appraisal and title report may also be required before the loan closes. These documents help establish the property’s value and identify liens or ownership issues that need to be handled through escrow.

Hard money is asset based lending, so the property itself remains a major part of the underwriting decision.

Investors Should Document Available Funds

Real estate investors should be prepared to show that they have the funds required for their part of the transaction.

Brad Loans asks investors for evidence of the down payment and available working capital. A bank statement can provide that information. If the property already produces rental income, copies of existing leases may also be relevant.

An investor should also have a clear idea of what happens after the purchase. A fix and flip borrower may plan to renovate and sell. A rental investor may intend to refinance into longer term financing.

That exit strategy does not need to be complicated, but the numbers should make sense before money is borrowed.

Owner Occupants Need Income Documentation

An owner occupied hard money loan has different requirements from an investor loan.

Brad Loans requires third party verification of income for owner occupied borrowers. Its current borrower information lists options including pay stubs, tax documents or, in some situations, bank statements used to establish income.

The lender also considers debt obligations when determining whether the proposed payment is affordable.

This is an important distinction because hard money does not mean that every financial requirement disappears. Consumer lending rules still apply when the property will be the borrower’s principal residence.

Bring Valid Identification

Borrowers need valid identification for the transaction and closing process.

Brad Loans states that it can work with United States and foreign identification and also considers borrowers using an ITIN number.

If a property will be purchased through an entity, additional business documents may be necessary. Ask before submitting the application so the title and borrower structure are established correctly from the beginning.

Cross Collateral Requires Information About Both Properties

Cross collateral financing uses equity in another property as additional security for the loan.

That means the lender needs information about more than the property being purchased. Brad Loans may offer up to 100 percent of the purchase price when sufficient equity in another property is pledged as additional collateral.

The additional property’s value, ownership and existing debt therefore matter. Title work may be needed on both properties because both can become part of the security for the loan.

Cross collateral can reduce the cash required for a down payment, but the borrower is placing additional real estate at risk. The structure and release terms should be understood before closing.

Insurance and Escrow Information Matter Too

A real estate loan does not finish with approval.

The title company coordinates closing and recording, while appropriate property insurance must be arranged before funding. Refinancing borrowers should be prepared to provide insurance contact information, and purchase borrowers should arrange coverage as required for the property.

Responding quickly when the lender, appraiser, insurer or title company asks for information helps keep the transaction moving.

Prepare for an Arizona Hard Money Loan With Brad Loans

Brad Loans by eMortgage provides hard money financing for owner occupied homes, investment properties, fix and flip projects, purchases and refinances throughout the Greater Phoenix area. Brad works directly with borrowers and can structure loans around a wide range of credit and real estate situations. If you have found a property or want to know what documents you should prepare before making an offer, call 602 999 9499 to discuss your situation and begin the prequalification process.

References

Brad Loans Frequently Asked Questions
Brad Loans Loan Programs

Brad Loans Hard Money Loan Application

Capital Fund 1 Arizona Hard Money Lending Process

Hard Money Loan Exit Strategy in Arizona

Hard Money Loan Exit Strategy in Arizona

Sell or Refinance? Building a Hard Money Loan Exit Strategy in Arizona

A hard money loan should be entered with a clear way out. The property may secure the debt, but the borrower still needs a practical plan for repaying the balance before the maturity date. For many Arizona investors, the main choice is selling the completed property or refinancing it into longer term financing.

That choice affects the repair plan, timeline, cash reserves and loan structure from the beginning. An exit strategy written after the project is already behind schedule is usually much weaker than one tested before closing.

Understand the Maturity Date

Some short term real estate loans require monthly interest payments with the unpaid principal due at the end. That final amount may be described as a balloon payment. The Consumer Financial Protection Bureau defines a balloon payment as a large one time payment due at the end of the loan term.

Read the note carefully and record the exact maturity date. Do not rely on a general memory that the loan lasts “about a year.” Build the project calendar around the written date and leave room for delays.

Selling the Property Can Be the Cleanest Exit

A fix and flip investor commonly repays the loan from sale proceeds. This route works when the repair budget is realistic, the after repair value is supported and the finished property can be listed with enough time to attract a buyer.

Work backward from the maturity date. Allow time for renovation, permits, final cleaning, listing preparation, marketing, buyer inspections, appraisal and closing. A signed purchase contract is not the same as a completed payoff because the buyer’s financing can still be delayed.

Price the finished property from current comparable sales rather than the profit you hope to make. An unrealistic asking price can turn a planned sale exit into an expensive holding problem.

Refinancing Requires Different Preparation

An investor who wants to keep the property may plan to refinance into a rental, commercial or conventional loan. The new lender may review credit, income, debt, leases, property condition, reserves and seasoning requirements differently from the hard money lender.

Begin talking with the long term lender early. Ask what property condition, occupancy, documentation and appraisal will be required. If the refinance depends on rental income, understand when a signed lease must be in place and how the new lender calculates that income.

Capital Fund 1 notes that a conventional refinance can take considerably longer than a hard money closing. The exact timeline varies, so the borrower should not wait until the final weeks of the current loan.

Build a Second Exit

Every project should have a reasonable alternative. A flipper may plan to sell but keep a rental refinance option if market activity slows. A buy and hold investor may plan to refinance but remain willing to sell if the property does not qualify or the new payment is not workable.

A backup plan must be more than a hopeful sentence. Check whether the likely rent supports the proposed refinance, whether the property could sell at a lower price and whether the borrower has cash to cover an extended holding period.

Watch for Changes That Weaken the Plan

Construction delays, cost overruns, a lower appraisal or slower sales market can change the exit. Review the numbers throughout the project rather than waiting for the original schedule to fail.

If the expected sale price drops, calculate the result after loan payoff and selling costs. If refinancing becomes less likely, ask why. Credit, income, property condition or debt may need attention before another lender can approve the new loan.

Communicate Before the Loan Comes Due

Brad Loans advises borrowers whose exit is not a property sale to make contact at least six months before the all due date to discuss possible refinancing, an extension if one is available, or financing elsewhere.

An extension is not guaranteed. It may involve new fees, conditions or underwriting. Early communication gives the borrower more choices than a call made after maturity.

Discuss Your Exit Strategy With Brad Loans

Brad Loans by eMortgage provides hard money, fix and flip, bridge, purchase and refinance options for Arizona property owners and investors. Each loan and property is reviewed individually, so the proposed repayment plan should be part of the first conversation. Call 602 999 9499 to discuss whether a sale, refinance or another documented source of repayment fits the property and requested loan term.

References

Brad Loans Frequently Asked Questions
Brad Loans Loan Programs

Consumer Financial Protection Bureau Balloon Payment Guide

Capital Fund 1 Hard Money Refinance Guide

Capital Fund 1 Hard Money Loan Exit Strategies

Fix and Flip Working Capital in Arizona

How Much Cash Do You Need Beyond the Down Payment for a Fix and Flip?

How Much Cash Do You Need Beyond the Down Payment for a Fix and Flip?
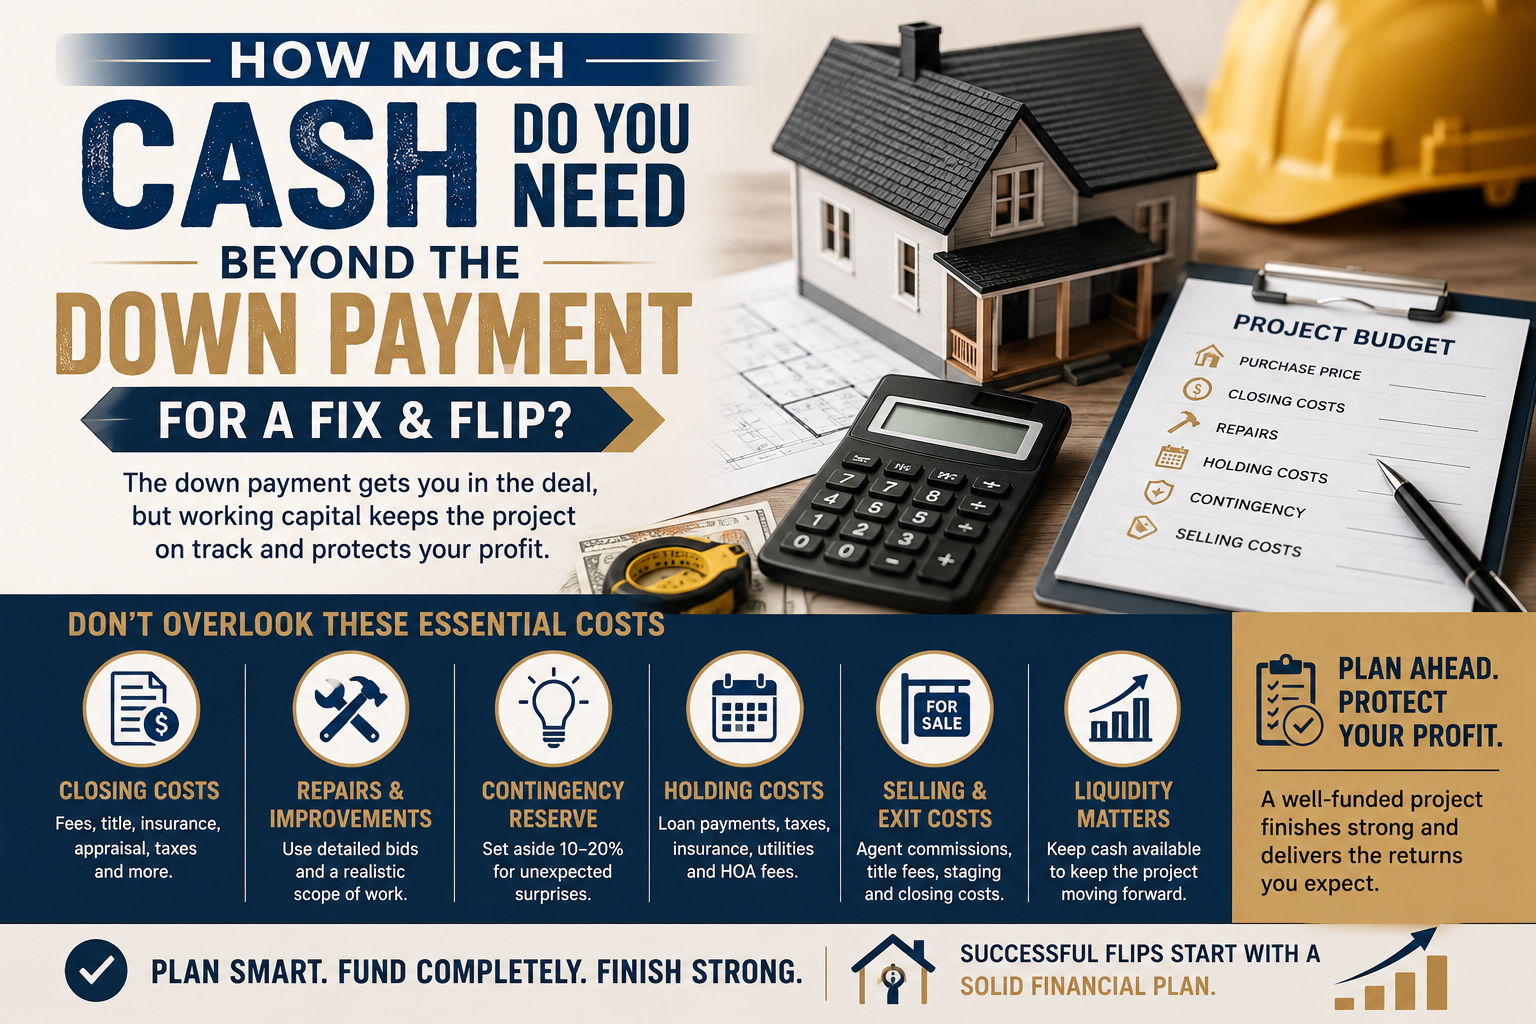
The down payment is the most visible cash requirement in a fix and flip, but it is not the only money an investor needs. A property can be purchased successfully and still run into trouble a few weeks later because the borrower has not reserved enough for closing, repairs, utilities or loan payments.
Brad Loans asks investor borrowers to show both the down payment and available working capital. That distinction matters. The down payment helps complete the purchase. Working capital keeps the project moving until the property is sold or refinanced.
Start With the Full Cash to Close
Ask for an estimate that separates the down payment from the other charges due at closing. Depending on the loan and property, those expenses may include lender fees, appraisal, title work, escrow charges, recording, insurance and prepaid taxes or interest.
Do not assume every fee can be added to the loan. Some costs may need to be paid before closing or brought to the title company in verified funds. Keep a margin between the estimated amount and the cash actually available.
Contractor Deposits Arrive Quickly
A contractor may need money for scheduling, demolition, permits, dumpsters, materials or subcontractors soon after the purchase closes. If the loan includes renovation funds, find out how and when those funds are released. Some programs reimburse completed work rather than advancing every dollar at the beginning.
The investor therefore needs enough liquidity to start the project and keep work moving between inspections or draws. A contractor who has to stop while waiting for money can push the entire schedule back. Competitor application checklists commonly request contractor bids, repair timelines and evidence of borrower reserves for this reason.
Build a Line by Line Repair Budget
A single figure marked “rehab” is not enough. Break the work into roofing, electrical, plumbing, heating and cooling, flooring, cabinets, paint, landscaping and other major categories. Include labor, materials, permit costs, debris removal and sales tax where applicable.
Use contractor bids and a property inspection rather than a rough guess based on another house. Older Phoenix Valley homes may hide electrical, sewer, roof or air conditioning problems that are not visible during a quick walk through.
Keep a Contingency for Surprises
A contingency is not spare money for upgraded finishes. It is protection against conditions that could not be confirmed before demolition. The amount should reflect the property’s age, condition, inspection findings and project complexity.
If every available dollar is assigned before work begins, one damaged sewer line or failed air conditioning system can stop progress. A realistic reserve gives the investor choices when the unexpected appears.
Count the Monthly Holding Costs
The property continues to cost money while it is being repaired and marketed. Include loan payments, property taxes, insurance, electricity, water, landscaping, pool service, security and homeowners association charges when they apply.
Estimate the holding period conservatively. A three month renovation followed by a quick sale may be the goal, but permits, contractor delays, inspections or buyer financing can extend the timeline. Run the budget for a slower outcome as well as the ideal one.
Remember the Cost of Selling or Refinancing
A completed house still has expenses before the hard money loan is paid off. A sale may involve agent compensation, title charges, repairs requested by the buyer, staging, cleaning and concessions. A refinance can require a new appraisal, lender fees, reserves and time for underwriting.
These costs belong in the project budget from the beginning because they affect the amount of profit or equity remaining after the loan is repaid.
Document the Source of Funds
Lenders may ask for bank statements showing the down payment, closing funds and working capital. Keep project money in accounts that are easy to document. Large transfers or recent deposits may require an explanation.
If another investor or business partner is contributing cash, discuss the ownership and repayment arrangement before applying. The lender and title company need to know who is involved in the transaction.
Plan Fix and Flip Financing With Brad Loans
Brad Loans by eMortgage offers Arizona fix and flip and investment property loans, including case by case options involving cross collateral when sufficient equity is available in another property. The team can review the purchase price, proposed repairs, available cash and exit plan before the investor commits to a deal. Call 602 999 9499 to discuss the complete funding picture, not just the down payment.
References
Brad Loans Fix and Flip Loans
Brad Loans How to Qualify
Brad Loans Loan Programs
Groundfloor Hard Money Loan Checklist
LendingBee Hard Money Loan Checklist

Translate »