Our News

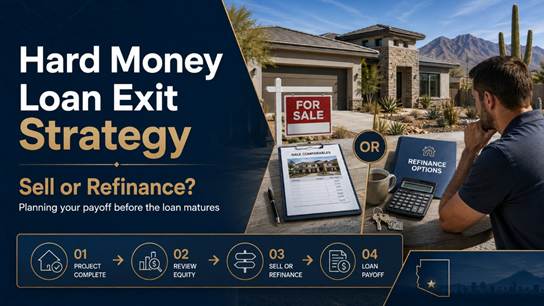
Hard Money Loan Exit Strategy: Sell or Refinance?

Hard Money Loan Exit Strategy: Sell or Refinance?

A hard money loan is designed to solve a short term financing problem. It may help an Arizona investor buy quickly, complete renovations or move forward when a traditional bank cannot meet the deadline. The loan still has to be repaid, often through a large final payment.

That is why the exit strategy should be decided before closing. Most borrowers plan to sell the property or refinance into longer term financing. Both routes can work, but each depends on timing, property value and changing conditions.

What Is a Hard Money Loan Exit Strategy?

An exit strategy is the plan for paying off the full loan balance. Monthly interest payments may not reduce the principal, particularly when the loan is interest only. The remaining balance can become due through a balloon payment at the end of the term.

The Consumer Financial Protection Bureau defines a balloon payment as a large payment due at the end of a loan. If the borrower cannot make it, selling or refinancing may be necessary. Waiting until the last moment can leave too little time to complete either option.

Selling the Property

Selling is the usual exit for a fix and flip project. The investor completes the repairs, lists the property and uses the closing proceeds to repay the lender.

This plan depends on more than the expected after repair value. The property must be finished on time, priced realistically and attractive to buyers. The budget should allow for agent commissions, title expenses, seller concessions, taxes and additional interest if the home takes longer to sell.

Build extra time into the schedule. A buyer can cancel, an inspection can uncover another repair, or an appraisal can come in below the contract price. A profit estimate with no room for delay is not a dependable exit strategy.

Refinancing Into a Longer Term Loan

An investor who intends to keep the property may refinance the hard money loan. The new loan pays off the balance and replaces it with financing better suited to a rental or long term hold.

Refinancing is not automatic. The borrower and property must qualify under the new lender’s rules. Credit, income, property condition, rental income, ownership history and the appraisal may all affect approval.

Start talking with the proposed refinance lender early. Brad Loans advises borrowers whose exit is not a sale to make contact at least six months before the all due date. That leaves time to prepare documents and consider another option if the expected refinance is unavailable.

Know the Payoff Amount

The principal balance is only part of the payoff. Ask the loan servicing company for a payoff statement that includes accrued interest, servicing charges and any other amount due through the planned closing date.

Confirm whether the loan has a prepayment penalty, extension fee or release price connected to additional collateral. Brad Loans states that its programs have no prepayment penalty, but every borrower should rely on the signed documents for the terms of a specific transaction.

Prepare a Backup Plan

An exit strategy includes a second route. An investor planning to sell may also explore refinance qualifications. Someone planning to refinance should know whether the property could be sold quickly enough to repay the balance.

Extensions should not be treated as guaranteed. A lender may choose not to extend, and an extension may involve additional cost. Track the maturity date from the beginning and review progress throughout the project.

Check the Numbers Throughout the Loan

Update the exit plan when the repair budget, completion date or expected value changes. Review the remaining loan cost, likely sale proceeds and time required to close.

If the project falls behind, act early. Reducing the scope, changing contractors, adjusting the resale price or beginning the refinance process sooner may preserve options that disappear near maturity.

Plan Your Arizona Hard Money Loan With Brad Loans

Brad Loans by eMortgage provides hard money loans for Arizona investors, property buyers and qualifying owner occupants, including purchase, refinance and fix and flip financing. The team can review the property, proposed repayment plan and available loan structure before you commit. Call 602-999-9499 to discuss your transaction and build a practical exit strategy from the start.

References

Consumer Financial Protection Bureau: Balloon Payments

Arizona Department of Insurance and Financial Institutions: Mortgage Lending
Fix and Flip Draw Schedule: Arizona Investor Guide

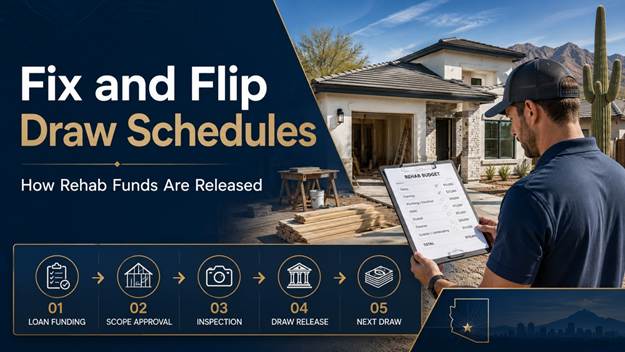
Fix and Flip Draw Schedules: How Rehab Funds Are Released

Fix and Flip Draw Schedules: How Rehab Funds Are Released

A fix and flip loan may cover more than the purchase of an Arizona property. Some programs also finance part of the renovation budget. The key detail is that repair money is not always handed to the investor at closing. It may be held back and released only after agreed work has been completed.

That arrangement protects the lender, but it also affects the investor’s cash flow. Before accepting a loan, understand when funds become available, what proof is required and how much working capital you need.

What Is a Fix and Flip Draw Schedule?

A draw schedule is the written plan for releasing renovation funds. Depending on the lender and project, money may be released after several construction stages or through one holdback paid after the approved work is complete.

The schedule should identify the repair budget, the work connected to each release and the process used to confirm completion. It may also explain inspection charges, minimum draw amounts and whether the borrower must pay contractors first.

Brad Loans describes a renovation program in which up to 70 percent of the combined purchase price and estimated renovation cost may be financed on a case by case basis. The purchase portion is released at closing, while financed renovation proceeds are held in escrow and released after the renovations are complete.

Why Lenders Hold Renovation Funds

A lender approves the loan partly because the planned repairs are expected to protect or improve the property’s value. Holding the funds helps make sure the money is used for the work in the approved budget.

For the borrower, the tradeoff is simple. The loan can include repair money, but the investor may still need enough cash or contractor credit to keep the project moving until funds are released.

Build the Scope of Work Carefully

The scope of work should be specific enough for a lender, contractor and inspector to understand what will be completed. Separate major items such as roofing, air conditioning, electrical work, plumbing, flooring, cabinets, paint and landscaping.

Use realistic costs based on written bids when possible. An estimate that is too low may leave the investor paying the difference. An inflated budget can also weaken the deal because the lender will compare total project cost with the purchase price and expected after repair value.

Arizona projects often reveal heat related problems with roofs, cooling systems, windows and exterior surfaces. Inspect those items before finalizing the budget.

Ask How a Release Is Approved

Do not assume that sending an invoice automatically produces payment. Ask whether the lender requires photographs, receipts, lien waivers, a site inspection or confirmation from an independent inspector.

Find out how long review and funding normally take after a complete request. A contractor who expects immediate payment may not be willing to wait for the lender’s process. Discuss the arrangement before work begins.

The loan documents should also explain what happens if the scope changes. Moving money between budget categories may require approval.

Keep Working Capital Available

Even when renovation costs are included in the loan, an investor should keep a reserve. Materials may require deposits. Contractors may bill before a release arrives. Hidden damage can appear after demolition, and holding costs continue while the property is being repaired.

Include interest, insurance, taxes, utilities, permits and possible delays in the project budget. A draw schedule does not remove the need for cash management.

Review the Exit Plan Before Closing

The renovation timeline should fit comfortably inside the loan term. Delays can reduce profit and bring the balloon payment closer before the property is ready to sell or refinance.

Compare the construction schedule, expected listing date and maturity date. Leave room for inspections, negotiations and a slower closing than expected. A strong project needs both a repair plan and a realistic repayment plan.

Discuss Arizona Fix and Flip Financing With Brad Loans

Brad Loans by eMortgage offers Arizona hard money financing for property purchases, fix and flip projects and renovation costs on qualifying transactions. Every property and budget is reviewed individually, so speak with the team before making assumptions about funding or release terms. Call 602-999-9499 to discuss your project and the loan structure that may be available.

References

Brad Loans: Loan Programs

Brad Loans: Frequently Asked Questions

Brad Loans: How to Qualify

Kiavi: Funding Your Fix and Flip With Hard Money

RCN Capital: Fix and Flip Draw Schedules Explained

Can You Get A Hard Money Loan With Bad Credit In Arizona?

Can You Get A Hard Money Loan With Bad Credit In Arizona?

Banks can be unforgiving. A borrower may have real estate equity, a strong investment idea, or a clear plan, but still run into problems because of credit history, self employment, past foreclosure, bankruptcy, short sale, or lack of traditional income paperwork.

That does not always mean the deal is dead. It may mean the borrower needs a different kind of lender.

Brad Loans by eMortgage offers hard money loans in Arizona, including options for borrowers who may not qualify through a traditional bank. Every loan is reviewed individually, but hard money can be useful when the property and collateral are stronger than the borrower’s credit profile.

Why Banks Say No

Traditional lenders usually follow strict rules. They look closely at credit scores, tax returns, employment history, debt ratios, reserves, and property condition. That process works for many borrowers, but not all of them.

A self employed borrower may make money but have complicated tax returns. An investor may want to buy a property that needs repairs. A homeowner may have equity but poor credit after a difficult few years. A business owner may need money quickly and have real estate available as collateral.

A bank may still say no.

How Hard Money Loans Work

Hard money loans are real estate backed loans. That means the property is a central part of the approval process. Instead of relying only on credit and income paperwork, the lender looks at the real estate, the equity, the borrower’s plan, and the overall risk of the deal.

Brad Loans states that bad credit, no credit, discharged bankruptcy, short sale, foreclosure, and non citizen borrower situations may still be considered. That is one reason hard money lending can be helpful for borrowers who have been turned down elsewhere.

It is still a serious loan. Borrowers should understand the rates, fees, loan term, monthly payment, and exit plan before moving forward.

When A Hard Money Loan May Help

A hard money loan may help with a fix and flip property, an investment purchase, a refinance, a bridge loan, a business loan secured by real estate, or a time sensitive real estate opportunity.

For example, an investor may need to close quickly on a property that needs repairs. A homeowner may need short term financing while working toward a longer term solution. A business borrower may own real estate and need capital for a specific purpose.

The common thread is real estate collateral.

Ask Questions Before Applying

Before applying, borrowers should ask how much they may qualify for, what property value is being used, what fees apply, how long the loan term is, and what happens if the exit plan takes longer than expected.

Good hard money lending should be clear from the start. Brad Loans encourages borrowers to call and discuss their specific loan options with Brad and his team.

Phoenix Hard Money Real Estate Loans

If you’re interested in getting involved with real estate investing and need the capital to purchase properties hard money is a great way to get started.  Brad Loans has extensive experience in both real estate investing and hard money lending and is proud to offer Phoenix Valley real estate investors the financing they need.  It is easy to get started applying for hard money loan and Brad Loans is able to work with clients with bad credit and no credit. We are your source for hard money when traditional banks say no.  Read more about Brad Loan’s hard money loan programs or get started fill out our hard money loan application or give us a call to ask questions at 602-999-9499.

Translate »